Azərbaycanca
 По-русски
 English

 About us
In Azerbaijan, the rules for issuing loans will change: what do borrowers need to know?
Be the first to know
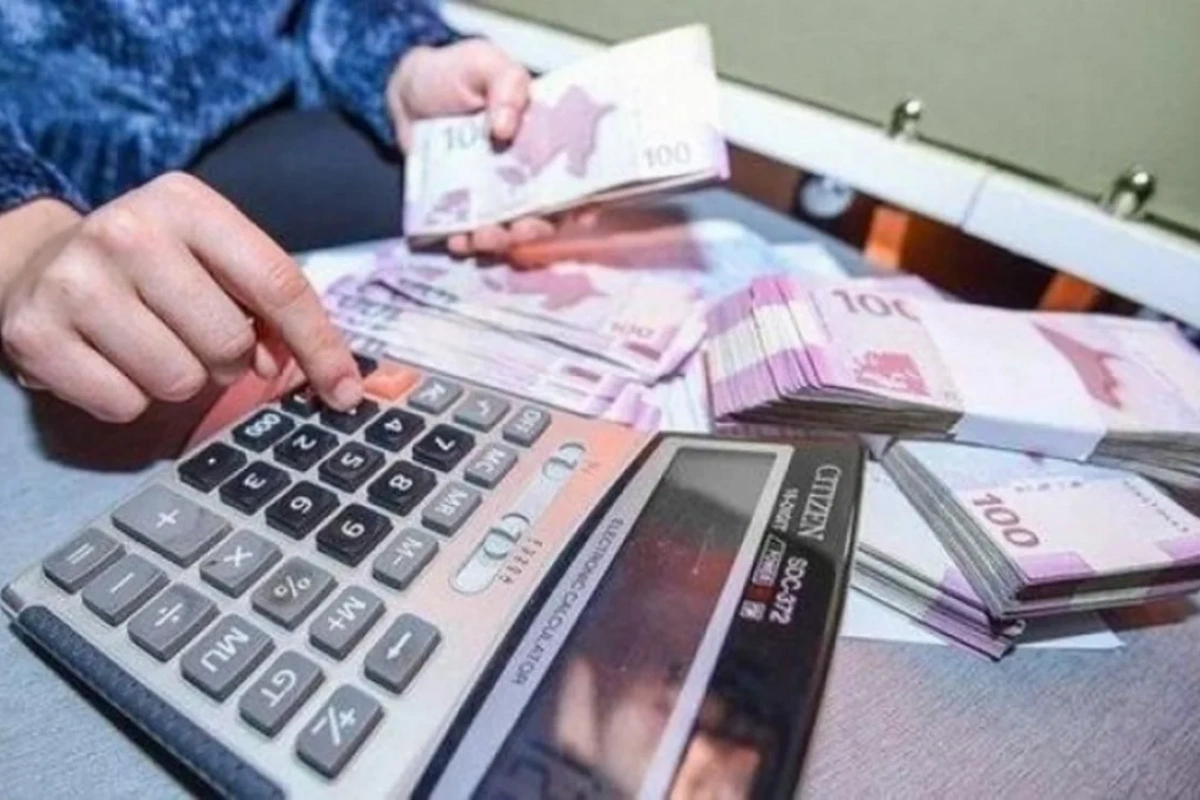
Starting from November 10, a decision establishing an additional criterion for evaluating loans issued to companies and individual entrepreneurs engaged in installment sales of goods will come into effect.
As reported by BAKU.WS with reference to Oxu.Az, a new evaluation criterion has been established for loans provided to companies and individual entrepreneurs carrying out installment sales of goods. Specifically, these entities will be required to provide the bank with information on the total volume of their installment sales portfolio and the number of buyers. The bank will cross-check this information against the corresponding data submitted to credit bureaus. If upon comparison, the correspondence on any of the indicators falls below 90%, such a loan will be classified as an unsatisfactory asset.
A loan issued based on a behavioral model is classified at the time of issuance as at least a watched asset.
In addition, according to the amendments, if a consumer loan is secured by a guarantee, the guarantor's debt-to-income ratio must not exceed 70%.
Changes have also been made to the provisions concerning the calculation of credit risks. In particular, loans issued based on a model and written off the balance sheet over the past 12 months will also be taken into account in the relevant calculations.
It should be noted that the new requirement regarding the guarantor's debt-to-income ratio will apply to credit obligations arising after the date this provision comes into effect.
For example, if the guarantor's monthly income is 1,000 manats, the monthly payments on their debt obligations must not exceed 700 manats.
A new requirement for calculating the borrower's income when issuing bank loans has also been established in Azerbaijan.
According to the amendments, if the borrower's income can be determined based on relevant documents or data obtained from state information systems, banks will not be allowed to forecast that person's income using a behavioral model.
For example, if a person has a salary certificate or their income can be determined from state information system data, the bank is not entitled to use income forecasted by a behavioral model in the loan calculation.
Similar News
SOCAR increased exports of petroleum products by 2.8% in Q3
In the third quarter of the current year, 657,421 tons of petroleum, petrochemical, and gas chemical products manufactured at the enterprises of the State Oil C...